Xoom: Send Money & Transfer

Screenshots
Details
- Rating
- 30.30K reviews
- Version
- 10.11.0
- Developer
- Xoom, a PayPal Service
Analysis by Norviv
I found Xoom most useful when I treated it as a focused way to move money internationally rather than as a complete everyday banking app. It is built for a simple need: sending funds from the United States to Mexico, India, and many other destinations through a mobile interface. In my experience, that narrow purpose is also its main strength. The app keeps the central task visible, while the important details—recipient information, delivery method, exchange rate, fees, and identity checks—still deserve careful attention before confirming a transfer.
Developed by Xoom, a PayPal Service, this free finance app has been available since August 8, 2012. Its Everyone content rating makes it approachable for a broad audience, although international transfers themselves require adult judgment because mistakes in names, account details, or destination information can be difficult to undo. The current version is 10.11.0, and it requires iOS 10 or later. On the popularity side, it has passed five million installs, with an average rating of 4.8 from roughly 363,000 ratings and around 30,000 written reviews. Those figures suggest a mature service that many people return to, but they do not remove the need to check each transaction carefully.
What using Xoom feels like in real life
The first thing I noticed is that the app is organized around the transfer itself. Instead of making me search through a large collection of financial tools, it guides me toward choosing a country, entering an amount, selecting a recipient, and reviewing the result. That is a sensible design for someone who may only open the app when a family member needs money or when a recurring household obligation comes due.
A realistic example would be sending money to a relative in Mexico after receiving a message that a utility bill is due. I would begin by checking the destination and amount, then confirm that the recipient’s name matches the identification or account information they will use. Before pressing the final button, I would compare what I am paying with what the recipient is expected to receive. That final review matters more than speed. A transfer that looks convenient can become inconvenient if the recipient has to correct a spelling error or if the chosen delivery option does not suit them.
The app is especially practical for people who already know their recipient and send money to the same country repeatedly. Once the basic relationship is established, the process can feel less intimidating than arranging an international payment through a traditional bank. For a first-time transfer, however, I recommend slowing down and reading every screen rather than assuming the app will automatically choose the best arrangement.
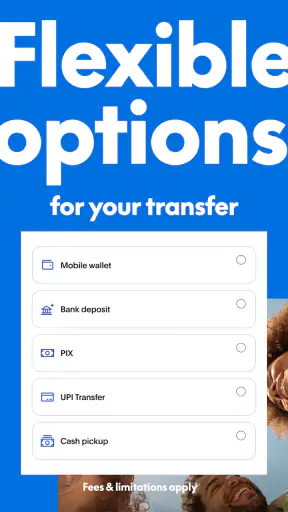
Its broad destination coverage is another reason it stands out. Xoom supports transfers to Mexico, India, and 145 countries in total, so it can be relevant to families, students, remote workers, and travelers with financial ties abroad. That reach does not mean every country works in exactly the same way. The available delivery choices, timing, required information, and total cost can vary by destination, so I would always treat the country-specific review screen as the source of truth for a particular payment.
The strongest part is the pre-transfer review
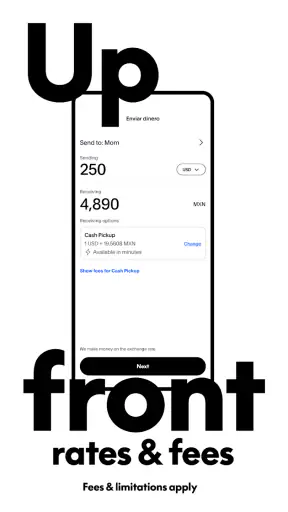
For me, the most valuable part of the experience is not simply entering an amount. It is the opportunity to inspect the transaction before sending it. International money movement involves more than converting one currency into another, and a useful app should make the practical outcome understandable. I pay attention to the amount leaving my side, the amount intended for the recipient, and any difference created by fees or conversion.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
This is where Xoom can be more convenient than a conventional bank transfer. A bank may make international payments feel like a specialist task hidden inside a larger account system. Xoom puts the transfer at the center, which helps when the user’s goal is simply to send money abroad. I also prefer seeing the recipient and destination connected to the transaction rather than relying on memory after moving between several banking screens.
That convenience comes with a responsibility: I do not compare services by looking only at an advertised fee. I compare the final amount the recipient should receive. A service with a low visible fee may still produce a less favorable result after currency conversion, while a service with a different fee structure may deliver more to the other person. Xoom is best judged at that complete, final-review stage.
Another useful habit is separating urgent transfers from planned transfers. If the money is needed immediately, convenience may justify using the workflow I already know. If the payment is routine, I can prepare the recipient details in advance and compare the displayed outcome with another reputable remittance service or my bank. This turns the app from an automatic button into a tool for making a deliberate choice.
Where it helps more than a bank or wallet
Xoom occupies an interesting middle ground. It is more specialized than a general digital wallet, but often easier to approach than a traditional bank’s international-payment area. A bank can be preferable when I need a broader record of domestic and international finances in one place, when the recipient is another bank account with established details, or when I already receive favorable terms through my account. A general wallet can be better when both people already use the same platform and the transfer stays within that ecosystem.
Xoom makes more sense when the sender and recipient are in different countries and the recipient may need a destination-specific way to receive funds. That is the practical distinction I would use when choosing it. I would not install it simply because it is a finance app; I would install it because the person I am paying and the country involved fit its transfer workflow.
It is also useful for people who do not want to expose their entire banking dashboard to a family member or who prefer to keep international remittances separate from ordinary spending. That separation can make the purpose of each transaction clearer. At the same time, users who want budgeting, investing, bill tracking, or a full checking-account replacement will find the app too narrow. Its value comes from doing one financial job directly, not from replacing every other financial tool.
The friction I would not ignore
The biggest weakness is that a quick-looking transfer can still require careful preparation. Recipient names, destination details, and delivery choices are not minor fields. If I rush because the interface feels simple, I increase the chance of creating a problem that the app cannot solve through design alone. The cleaner the screen looks, the more important it is to remember that the underlying transaction remains consequential.
Costs and exchange rates are another point where I would avoid assumptions. The amount shown to the recipient can change depending on the destination, funding arrangement, currency, and delivery method. I would not decide that Xoom is cheaper than a bank or another remittance service without entering the exact amount and comparing the final result. This is a meaningful limitation for price-sensitive users: the app may save time, but convenience is not automatically the same as the lowest overall cost.
Verification can also interrupt the flow. Financial services need to confirm that a transfer is legitimate, and a user should expect that an unfamiliar transaction or a new recipient may involve additional checks. I see this as a reasonable part of a money-transfer service, but it can be frustrating if I am trying to send funds at the last minute. My practical advice is to set up the app and understand the process before an emergency, rather than making the first attempt when someone is already waiting.
There is also a human limitation that no interface can remove: the recipient may have different expectations from the sender. One person may assume the money will arrive in an account, while the other expects another collection or delivery arrangement. I would agree on the receiving method before starting. That small conversation prevents a surprisingly large amount of confusion.
Small workflow choices that make a difference
My first tip is to create a personal checklist before each transfer: destination country, recipient’s legal name, amount, intended currency, and preferred receiving method. I would not copy details from an old message without checking them again. People move, change accounts, and update identification, while a saved or repeated recipient can make an outdated detail feel trustworthy.
My second tip is to use the review screen as a comparison tool, not just a confirmation screen. I would enter the intended amount, note the recipient’s expected result, and then compare that complete outcome with a bank or another established service if the payment is large or recurring. This is more informative than comparing a headline fee because it includes the practical value of the conversion.
My third tip is to separate recurring support from one-off emergencies. For regular family assistance, I would keep a consistent record of the date, amount, recipient, and purpose outside the app so I can recognize unusual activity. For an emergency, I would confirm the recipient through a separate communication channel before sending. A message that appears to come from a family member can be misleading, and the app itself should not be treated as proof that the request is genuine.
A fourth useful trade-off concerns speed. If the recipient needs money urgently, I may accept a more convenient delivery arrangement after checking the total cost and expected availability. If there is no urgency, I have more reason to compare options and verify every detail. Xoom is strongest when its convenience matches the situation; it is less compelling when I have plenty of time and another service offers a clearly better final amount.
Who should use it, and who should look elsewhere
I would recommend Xoom to someone who regularly sends money across borders and wants a dedicated mobile workflow. It is a good fit for people supporting relatives in Mexico, India, or another supported country, as well as users who need a straightforward way to organize an international transfer without navigating a full bank application. The app’s large user base and high average rating also make it feel less experimental than a newly launched remittance product.
It suits a sender who is comfortable checking transaction details and communicating with the recipient before payment. That point is important because the app can make the process easier, but it cannot decide whether the recipient’s information is correct or whether the transfer request is legitimate. Users who pay attention to those details will get more value from the convenience.
I would suggest looking at alternatives first if the main priority is the absolute lowest cost on every transfer, especially for large or frequent payments. I would also choose a traditional bank when account integration, consolidated statements, or an existing bank relationship matters more than a dedicated remittance experience. A wallet may be simpler when both sides already use the same service and no international delivery arrangement is needed.
People seeking a complete personal-finance center should skip Xoom as their primary app. It is not the tool I would choose for tracking spending, managing a portfolio, or replacing a daily banking relationship. Its focused design is a benefit for international transfers and a limitation for everything outside that task.
My final view after weighing convenience against care
Xoom succeeds because it makes international money transfers feel more approachable than they often do through ordinary banking channels. The country-focused flow, recipient-centered process, and clear opportunity to review the transaction are meaningful strengths. I especially appreciate that it can serve a recurring family-support routine without requiring me to turn the app into a larger financial system.
Still, I would not describe it as a set-and-forget solution. Fees, exchange rates, delivery choices, verification, and recipient details all deserve attention. The right question is not simply whether the transfer can be started quickly, but whether the final amount and receiving arrangement are right for the person on the other end.
For me, the verdict is positive with a clear condition: Xoom is a strong specialist for careful international senders, not a universal replacement for a bank or wallet. It is free to install, rated for Everyone, and backed by the developer Xoom, a PayPal Service. If I needed to send money abroad to a known recipient and the displayed terms suited the destination, I would be comfortable using it. If the transfer were unusually large, highly price-sensitive, or better handled through an existing bank relationship, I would compare alternatives before committing.
That balanced approach is the best way to use Xoom: Send Money & Transfer: let it simplify the mechanics, but keep the final financial judgment in your hands.
Frequently Asked Questions
01What is Xoom: Send Money & Transfer used for?
Xoom is a money-transfer service from PayPal that lets users send funds internationally, pay selected bills, and sometimes reload prepaid mobile phones. After installing the app, you can choose a destination country, enter the recipient’s information, select an available delivery method, and review the exchange rate, transfer fee, and estimated arrival time before confirming the transaction.
02Is Xoom safe and trustworthy for international transfers?
Xoom uses security measures associated with PayPal, including account verification, transaction monitoring, and encrypted connections. However, no financial service is completely risk-free. Before sending money, check that the recipient’s name and delivery details are correct, avoid sharing verification codes, and only use the official app from Google Play or the Apple App Store. Availability and protection can vary by country and transaction type.
03How much does Xoom charge, and what exchange rate will I receive?
The total cost depends on the sending country, destination, payment method, transfer amount, currency, and delivery option. Xoom normally displays the transfer fee, exchange rate, and the exact amount the recipient will receive before you submit the payment. Fees and rates can change, so it is worth comparing the final delivered amount with other reputable services rather than looking only at the advertised transfer fee.
04How long does a Xoom transfer take to arrive?
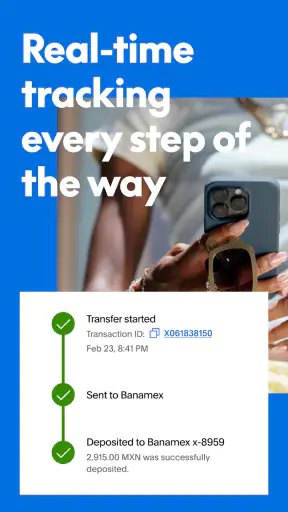
Delivery times vary according to the destination, local financial institutions, holidays, compliance checks, and the selected method. Some transfers may arrive within minutes, while bank deposits can take longer and cash-pickup availability depends on the local provider. The app usually shows an estimated delivery time during checkout and provides status updates, but estimates are not guaranteed in every situation.
05What information and payment methods are required to use Xoom?
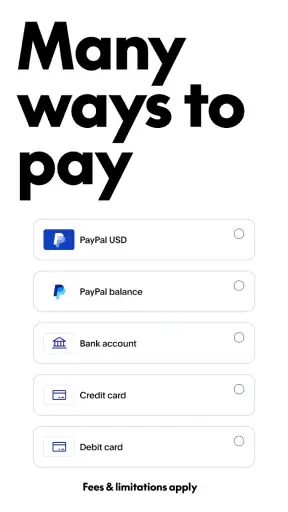
You generally need a Xoom or PayPal account, a valid payment method, and accurate recipient details such as their legal name, phone number, address, or bank information, depending on the service selected. Xoom may request identity verification or additional documentation before processing a transfer. Supported cards, bank accounts, and delivery options differ by country, so confirm eligibility inside the app.


